About sixteen years ago, I met him for the first time. My trainwreck sibling brought home this adorable puppy he had no business adopting because he had not one thing in his life that wasn’t a mess. I was furious at my sibling – he didn’t even take care of himself, how could he drag
Read More
June 2, 2009
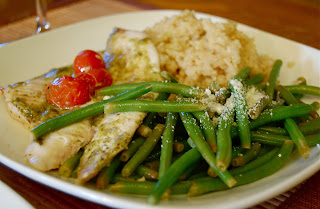
- I’m getting better at this cooking thing. Dinner creation: sole, quinoa cooked in a rice-like fashion, and lemon butter haricot verts! [Right, green beans. But the schmancy packaging said haricot verts.]
- And I made a luscious lobster macaroni and cheese, which I forgot to capture on digi-film because we dug in so quickly. It might even be better than my last favorite mac’n’cheese incarnation. I can think of a few changes I’d make to it, though.
- We saw UP this weekend. It was so good. Very cute, moving, a little sad (yes, I teared up), but very good.
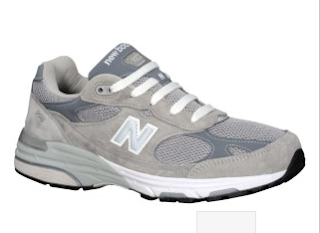
- New shoes, 35% off, filed under budget-cheat because they were a gift. They won’t be the multi-purpose walking/casual shoes I was really looking for, but that’s ok because these 993s hug my heels and support them like a good friend. And yes, 35% off is hardly my style when the shoes still ring up to $95, so I can only take my solace in knowing that we clocked in the world’s shortest shoe shopping expedition. Walked in, looked at the wall for a minute, pointed at the ones I wanted. Not counting the time it took Dorky Sales Guy to find the shoes, the selection and decision process took 7 minutes, tops.
- New 1/2 sleeve button down shirt for work, on sale and another 20% off because the shirt was missing a button. Silly people: the shirt comes with an extra button! But of course no big-box retailer is going to pay their employees to sew on a button to save $5. So I will! Thank you.
- And my PF blogger win? We sprung for the 3-D tickets because it was an earlier showing. We used premium movie passes worth $10.50 each, and paid the 3-D surcharge ($5) with a gift card. Total: $26.50. I’m not sure what kind of math they were using for that, though, because 21+5=$26. Except we got to the theatre a little late and the place was packed to the rafters; the only empty seats were in the front row. We’re too old for that nonsense, so we went to Customer Service to exchange the tickets for a later, non 3-D showing. I offered the CS rep our gift card to replenish with $5, and waited. And waited. And waited some more. I could see he was having trouble, at one point fumbling with his own wallet, and I started to grin evilly.
I had no intention of causing trouble for the poor guy, I was just trying to save him the use of a new gift card! But, evidently, as the sweat beads formed on his forehead, I realized he didn’t know how or simply couldn’t add the $5 to the card. He returned with two tickets in hand for the later showing, a free movie voucher card, and said “it’ll be just a minute.” My friend was happy, willing to walk away with the free movie voucher which was worth another $9.50. I, however, stood firm. If nothing else, I insisted, he had to return with the gift card – we still have $5 on that thing and that’s cash value! I don’t care if the value of the voucher was almost equal to the $10 in GC that he owed, I expected that gift card with $5 back. Friend thought I was pushing it, I simply smiled and shooed him off.
Five minutes later, the discombobulated fellow returned, flush with apology, another free movie pass, and the original gift card. I graciously told him not to worry about it, confirmed that the gift card still had the remaining $5 on it, and walked away with two free movie tickets, worth $10 each, in exchange for the “loss” of a $5 value on the gift card.
I could probably have suggested that he simply load up a new card, but that would have been pushing it. He needed to towel off as it was. 🙂
May 31, 2009
| Retirement Savings |
Roth IRA: $3,843
401(a): $7,226
403(b): $16,471
Total: $ 27,540 (24,972)
|
| Emergency Savings |
Catastrophe: $ 29,594
Problem Cushion: $ 1,000
Total: $ 30,594 (30,352)
|
| Short Term Goals |
Car Maintenance: $1,068
Insurance: $2,541
Travel/Con: $401
Taxes: $3,369
Moving: $3,472
Total: $ 10,851 (10,842)
|
| Long Term Goals |
House Down Payment: $101
|
| Investment Loans |
Prosper-ish: $12,630
Personal Loan: $2,000
Savings Bond: $362 (current accrued value)
Total: $ 14,992 (14,992)
|
| Total Assets |
Illiquid: $ 27,540
Semi-Liquid: $14,992
Liquid: $30,594
Expense Acct: $9,540
Goals Savings: $10,851
Total: $ 93,517 (91,118)
|
| Debt and Liabilities |
AX: $154
Chase: $1,850
Rent: $0
Total: $ 2,004 (2,187)
|
| Net Worth |
$ 91,513 (88,931)
|
There wasn’t a whole lot of change this month other than dumping more into my retirement accounts. I did spend a lot, though, and I’m relieved that the damage doesn’t appear to be much worse.
The end of next month should be much more exciting!
Addendum: Clearly, I was too lazy to make any real comments when I first posted this. The overall numbers look goodish, but the reality is I saved next to nothing in cash, and spent a lot. More than half the credit card balance is covered by the car insurance fund, but the absolute numbers are still ridiculously high for someone approaching unemployment.
I’m not fussing about it, but I am publicly noting that the spending needs to stop or slow down to a trickle.
On the other hand, I AM flush with cash enough to be much more flexible in my approach to paychecks and bills. I kicked up my 403(b) contribution for one paycheck to the max, which leaves me with next to nothing in my second June check. There’s plenty of money in the expense fund, so that’s no sweat. And I’m getting my final check, complete with vacation hours, two weeks after the non-check, so there’s really no stress on that front. Being responsible is so worth this flexibility!
May 30, 2009
Ah yes, hindsight. I knew this layoff was coming, most likely mid-year, yet it took me until April to start making appropriate adjustments.
Earlier this year, it was important to have cash on hand, so I cut back on retirement contributions to a bare-bones 3% (not including company match, which was maxed). My reasoning at the time was sound, but flawed due to incomplete knowledge.
Error One: I’m entitled to severance equal to one month pay when I separate from this employer, as well as over 200 hours of vacation pay. Didn’t take that cash payout into consideration. I made this assumption because I hoped to quit before the layoff which would have meant no severance.
Error Two: For another, my cash savings program was much more successful than anticipated. In January, I had $7000 for routine monthly expenses and $23,000 in savings. Since then, I’ve added ~$10,000 to those accounts, all while still paying bills. I could have spared a few thousand for retirement savings, considering the “sale prices” of the past several months, without being cash-poor & investment-rich post-employment.
Error Three: I didn’t consider that I’d be eligible for unemployment, and that it’ll cover all my monthly bills. At the time the plan was conceived, monthly expenses were well over $2000/month, so I estimated needing at least $35,000 in cash for 12 months of unemployment. In the meantime, the truck was sold, the family car was totaled and if nothing else, my monthly needs improved tremendously thanks to both events.
Being that pessimistic means I have an unusual stash of cash, just sitting around, while only having made just a little over $2000 in retirement contributions. Ergh. I hate throwing away both the opportunity to invest at lower prices and the tax benefit.
Don’t get me wrong, I’m certainly not bemoaning doing better than expected, for heaven’s sake. I’m just wishing I’d done a little better at making decisions based on the long-term, or at least considering the whole fiscal year. I subscribe to the “hope for the best, plan for the worst” mentality, but I clearly need to work on my automatic worst-worst-worst case scenario planning reflex. It’s a little dire. After all, it’s not like it’s the Zombie Apocalypse.
Of course, I haven’t hyperventilated about being a bag lady in a while, so maybe that was necessary for peace of mind.
For now, I’ll make a small adjustment to my contributions for the last check and leave payroll alone. Maybe I’ll make a few smaller investments, in addition to the CD I just bought. No sense in fussing too when we have so little time left, not until I learn how to read the future!
[Dear Magic 8-ball: will I find a good, well-paying job with benefits adjusted for COLA this year? What’s that? “Concentrate and ask again”? Hmph. I prefer Neil Gaiman‘s Magic 8-ball. I miss it.]
May 29, 2009
I’ve just locked up $10k in a one year CD.
It would have been more prudent to ladder them, but there aren’t any rates that are worth locking up the money for any amount of time apart from the one year term for which I’m earning a whopping 2.25 APY. At that price, it’s still twice as much interest as the formerly high-yield online savings accounts. Remember when those were the five magic words? I loved saying it, back in ought-one, the days of 5.35% APY: High-Yield Online Savings Accounts. Mmm…. delicious.
Oh, right, back to reality. What a drear existence for cash monies these days: interest-bearing checking accounts are barely registering on the interest scale at 0.10%.
This was what you could call an impulse investment. It wasn’t a scientifically, mathematically or otherwise analytically sound decision based on how much money I could afford to have locked away for 12 months. It was a nice round number, and I figured in a mental, back of the envelope calculation that it leaves me with approximately 20K in savings. That’d get me through 12 months of no income before breaking into the CD. (Worst case scenarios around here, all the time.)
Works for me.
How about you? What are you doing with your money? Or is it just lollygagging about like the rest of mine?
May 28, 2009
Fighting the good fight against credit card debt:

I was checking out my Etsy purchase and switched to the credit card option because I never use debit when avoidable when this screen popped up. The novelty was enough to make me stop and read it.
I was sure that it was because PP makes more on bank account funded payments than credit cards, and assumed that the sellers would assume that cost, but it looks like they charge the merchant the same fees:

Which probably does mean that, assuming PayPal is subject to the same merchant transaction fees that individual merchants pay, they’re eating the cost. No wonder they encourage the buyer to use their bank accounts! But how nice of them to remind us that interest charges aren’t desirable.
May 27, 2009
Just when it seemed like things were moving along swimmingly, I got the following notices in quick succession last week:
WAMU Investments: My rolled-over account is still alive, with 2 cents in it.
Ugh! Is it unreasonable that I just want m’darned account closed for good? No. No it’s not. Not long after the letter arrived, I saw that the brokerage account had been converted to a Chase account. Maybe I can get the two cents applied to my credit card balance. 😛
Citibank: My CD expired on May 15th and I have to call or send a letter via postal mail to make arrangements.
Why can’t I just log into my account and click on a box that says: cash out my CD! or Rollover! The CD department had the nerve to question my cashing it out saying, “we have excellent interest rates, and you won’t be earning nearly as much interest in your checking account.”
Uh, I’m not an idiot. I’m not leaving that money in my checking account, duh, and your interest rates are Not Nearly Awesome Enough. Hmph! I was perhaps a little huffier than the situation called for since I was in no mood to hear a sales pitch.
Prudential: A letter in the mail stated that they never received my long-form and that my application was being closed. Lies! I’d already gotten a letter from my employer stating that my increased life insurance was approved and in effect. But I called anyway to be sure, and found that sure enough, my policy is in force. Chalk another one up for wasting my time.
********************************
Emigrant Direct: In a fit of pique, I started to transfer all my money out. Except it gets marginally more interest (0.05%) than ING Direct, and they’ve both peeved me something special with their blockage of Yodlee. So I guess most of that money can stay put. But I feel like locking up about 10K in a CD at 2.25% APY. No, it’s not great, but it’s a full percentage point above my Citi savings accounts.
********************************
Today’s the day. Y’know. The Day.
May 26, 2009
Are y’all tired of clothing posts, yet? How about we change gears to something even more mundane? Groceries!!
That’s right. Groceries are wonderfully life-sustaining and delicious. I’m happy anyway.
The Target run was ostensibly only to get *ahem* stockings, otherwise known as thigh-highs, for my skirt suit. I’m gonna need to be demure and professional-like sometime this week. As you may know.
In the checkout lane, I remembered that last week I promised myself one bag of candy. (What? I never buy candy.) I’ve been suffering from Snickers mini/Kit Kat deficiency. This could turn into a serious problem, and prevention is the best defense! Or something like that. Non-spending fail, but that won’t be what I think when I reach into the candy pocket of the purse and find Transformer Snicker Minis! It remains to be seen if the yellow nougat freaks me out.
As usual, giving this mouse one goody meant that it almost turned into a major case of impulse buying: the baked sea salt and vinegar chips were irresistible, Colby Jack string cheese sounded perfect …. luckily, friend was on the phone with me and told me to Leave Now. I even managed to put the goodies back, as well.
The trip to the local grocery went a little better, nutritionally speaking. Fresh corn on the cob was on sale, 4/$1. Corn = summer, and good deals on corn are even better. That’s what the green beans (1/2 lb), oranges (2), bananas (3), whole wheat bagels (6), and eggs (12) are for. My grocery shopping can be a bit haphazard, if you can’t see a meal in there, not to worry. Neither can I.


