About sixteen years ago, I met him for the first time. My trainwreck sibling brought home this adorable puppy he had no business adopting because he had not one thing in his life that wasn’t a mess. I was furious at my sibling – he didn’t even take care of himself, how could he drag
Read More
November 5, 2008
For weeks I’ve been reading about the tightening credit market in response to the crises that abounded, and I wondered how long it would be before we experienced it in our daily finances.
Lackluster loans, both auto and mortgages, isn’t a problem as the idea of taking on debt in this economy is right out. I do, however, have fairly extensive credit card lines and decided to start trimming them back just as Citi decided the same. One of my older cards was canceled outright by Citi for inactivity, and I moved another hefty credit line to an active account and canceled a second card.
Yesterday’s mail brought a notice that Citi Premier Pass cards are being discontinued and changed to CitiBusiness cards. The draw of the Premier Pass was the Thank You flight points which effectively doubled my point earning on regular purchases, so I have until January 19th to earn as many spending points as I have flight points, freeing them up, and canceling that card since the CitiBusiness doesn’t offer rewards I’m interested in.
I may voluntarily trim back a couple more cards, perhaps another Citi and another Chase card, just to clean up the credit card landscape further. I don’t depend on them, anyway, except for rewards and cash flow purposes: I spend much less using credit cards than cash and it’s a great tracking tool.
I’ll keep my Citi Driver’s Edge because I have about $130 in rewards and I’m earning Drive Miles as well, so that supplements my car maintenance account. The AmEx Hilton is used for cell phone bills and dining out for hotel points; someday I’ll have enough points to go on vacation! The Chase Cash Plus card is excellent for generating 5 points per dollar spent on gas, groceries, and drugstores, while the Citi Diamond Preferred is still giving me 2 points per dollar on all other purchases. In all, four cards cover any and all spending. Extra cards are just on rotation for negotiating leverage when I want better rewards – I used to let them know that I was looking to cancel for better rewards and bonus points. Nowaways, retention may not be as diligent or generous, though.
Have you begun to experience any sort of credit limitations? Does it bother you at all?
November 4, 2008
Wanda at Well-Heeled‘s trying out a new game called Emergencyopoly which, as it turns out, is a game (slightly altered) that I’ve been playing for the past few months. I won’t rehash the update here, but it amuses me that this article from Savvy Sugar on back-up plans coincides with the theme of preparedness and a question we’ve all been asking ourselves:
What’s your backup plan? What does your parachute or lifeboat look like when the plane/ship goes down? If you lost your job tomorrow, do you know what you’d do? What are you doing right now to prepare?
Some answers I’ve heard:
1. Look for another job, doing anything necessary to pay the bills.
2. Take the leap to do something I’ve always wanted, but was too afraid to leave my job for.
3. *pointed to me* Hang onto Revanche as she walks out the door. [double take] “What?”
Yes, someone actually said I was their backup plan. Hah!
November 3, 2008
| Retirement Savings |
Rollover IRA: $1,452
Roth IRA: $3,653
401(a): $4,107
403(b): $12,197
Total: $ 21,409 (23,352)
|
| Emergency Savings |
Catastrophe: $ 19,743 (18,547)
Problem Cushion: $0
|
| Short Term Goals |
Car Maintenance: $810
Car Insurance: $1,503
Travel/Con: $297
Taxes: $3,499
Moving: $15
Total: $ 6,124 (5,184)
|
| Long Term Goals |
House Down Payment: $100
|
| Investment Loans |
Prosper-ish: $12,630
Personal Loan: $5,000
Savings Bond: $357 (current accrued value)
Total: $17,997
|
| Total Assets |
Non-Liquid: $21,409
Semi-Liquid: $17,997
Liquid: $19,743
Expense Acct: $6,683
Goals Savings: $6,124
Total: $ 71,686 (72,762)
|
| Debt and Liabilities |
Truck: $3,133
AX: 130
Citi: $403
Chase: $578
Rent: $1,360
Total: $5,604
|
| Net Worth |
$66,082 (66,846)
|
Notes:
Meh. I totally didn’t feel like putting this together.
Gains in cash holdings were more than offset by the losses of my portfolio. *shrug* Knew that was going to happen.
It’s more than time to cultivate more streams of income by freelancing if I want to make any actual gains. A six figure net worth seems much farther away than it did before.
Looking ahead to November:
1. It’s open enrollment time!
A) Figure out new FSA allocations for 2009. Account for increase in copays (up from $15 to $20 for office visits and up from $10 to $15 for prescriptions).
B) Long term care insurance. Do it.
C) Expand disability insurance? Hmm.
D) Anything else?
2. Am a little tweaked about the Thanksgiving holiday weekend. I’m in dire need of a getaway and Turkey Day takes up a whole weekend that could have been mine, all mine. Selfish, huh? Oh well, I’ll think of something because I really need a break.
Just read this NY Times article, Forming a Club to Share Financial Wisdom:
I’ve long lamented the fact that there aren’t as many money clubs as there are book clubs. Plenty of us would be more successful in meeting our financial goals if we met regularly with a small group of like-minded people to lay our finances bare, from incomes to debt to our spending foibles. It would be one part Debtors Anonymous and one part Weight Watchers, a bit like the investment clubs that were popular in the 1990s but with every part of our financial lives under the microscope.
What I didn’t do, but should have, was try to inspire an international movement around the idea. That’s what five women from Vancouver are trying to do with their new book, “The Smart Cookies’ Guide to Making More Dough” (Delacorte Press), and Web site, smartcookies.com.
Much of the book offers fairly basic financial advice, and it will probably resonate best with young women. The silly name, meanwhile, might turn off serious-minded people.
But that would be too bad, because theirs is a story of guts and grit, of five women who leaned on one another to rein in individual money habits that were fairly destructive.
At first I thought, that’d be awesome! And it would be. But what I’d want even more than a money club is a career club, one with members at various stages of their careers. I’d certainly love to get together with people who are financially wise for cross-mentoring but I’m at the stage where, mostly, I’ve got a good handle on the basics and much prefer to discuss at more advanced levels topics like career planning, investing, understanding the stock market, estate planning, insurances, real estate, etc. (Heh, estate planning. I plan to have an estate, someday.) This blog and reading about a hundred other PF blogs scratches the personal aspect of my finance itch rather well whereas I’m ripe for professional development.
What do you think? Would you want to start a money club? Or is there some area or topic that would more effectively contribute to your life?
October 31, 2008
In a fit of craftiness, I amateurishly cut up my nerdy-as-all-get-out gamer X-men Legends sleep shirt and made it a strapless dress.
There was an in-between phase when it was a t-shirt dress and it was infinitely cuter, because I’d inadvertently sewn perfect armholes, but it was too short. In my brainstorm, it was meant to be strapless to make it long enough to be decent, but I liked the interim phase much better, had I been able to stretch the material lengthwise, somehow. Unfortunately, that middle phase photo is lost and gone forever (dreadful sorry, Clementine) because I’m daft and took the photo without a memory card.
Before:

After:
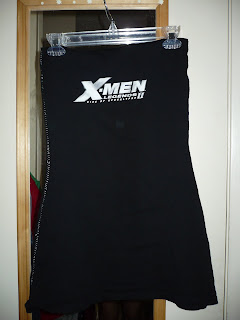
Note: In the making of this shirt, I’ve discovered that I’m a terrible tailor and depend entirely on luck. And, had it not been too short, it would have fit as a tshirt dress, so depending on luck isn’t actually a terrible plan (see: armholes). But it was too short. So never mind that.
get a free shower gel with any $10 purchase (good for in-store purchase only). Expires 11/05/08. I don’t shop there anymore, but if you were planning to anyway, remember to take this coupon along for an extra treat!

October 30, 2008
On days when I can’t shake a massive headache, like every day this week, or when aches and pains of any other sort are plaguing me, wee little steps are enough.
The following companies will no longer be sending me paper statements:
Wamu/J.P. Morgan Chase (2)
Citibank (6, plus the 5 linked credit card accounts)
AT&T
Emigrant Direct (4)
ING Direct (4)
I was thwarted again by American Express – they want some number that I gave them at the time of opening my account — 7 years ago. I haven’t a clue what they’re talking about so that’ll require a phone call.
Happily, my Vanguard accounts were switched to paperless some time ago, saving me $10/year on my Roth IRA. I need to rollover my really old Rollover IRA from Wamu, it once cost $15/year, but now it’s shot up to $25.


