About sixteen years ago, I met him for the first time. My trainwreck sibling brought home this adorable puppy he had no business adopting because he had not one thing in his life that wasn’t a mess. I was furious at my sibling – he didn’t even take care of himself, how could he drag
Read More
November 1, 2010
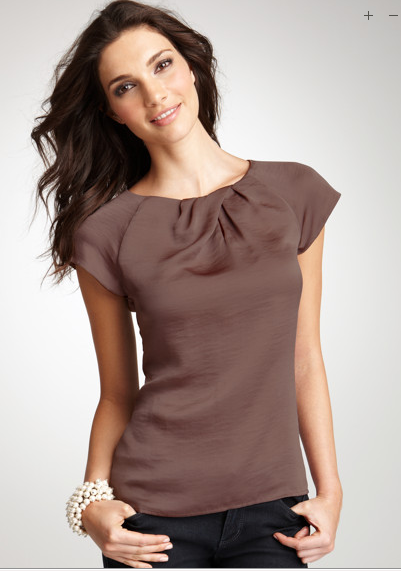
I splurged a bit after all. I gifted a few Scott Pilgrim books, picked up a few more long sleeve shirts on sale from Ann Taylor as layering pieces (previously mentioned), and splurged on this lovely top:
[$40, 50% off]
I feel a little sheepish because I really wanted the OMG Books shirt but this one grabbed my attention while I was ordering the much needed work shirts and now I feel like I’ve hit the limit on acquiring stuff.
Returning is always an option but it does fill a gaping area in my wardrobe between completely casual tees and button down long-sleeves.
As I ponder, I’m grateful I even have the choice considering my friends Sense to Dollars and eemusings recently discussed the lack of a generous returns policy in New Zealand. Without that option, I would certainly never have ventured to even buy it in the first place.
Until I started working and truly needed business clothes, my shopping had become so sporadic that I’d well gotten out of the habit of buying and holding. Stores like Ross and Marshalls are great but so rarely turn up gems that are both bargains and fit well that I’d basically given up on them for anything but housewares.
So while the professional side of me is grateful to Well Heeled for introducing me to petite fashion bloggers like Petite Asian Girl and Alterations Needed, the frugal PF blogger in me is distinctly uncertain about this whole other world of shopping where people my size actually can, for a price, find clothing that fits and flatters or make it fit and flatter. It’s probably a good thing that I’m used to spending on a budget … or rather not spending because I’m on a budget.
Here’s the real question: Keeper, or no? Fits really well. Could be paired with … things. Ah yes, check out my fashion sense!
{————Carnival————}
My thanks …..
to Flexo for hosting this week’s Carnival of Personal Finance and including my post Scammy scam scam?
October 31, 2010
Back on the horse!
Contrary to last month’s assertion that I was going to just move forward and not look back, I took some time to fill in all the blanks of the past weeks’ spending and income. It didn’t take more than an hour or so and helped PiC and I have a good conversation about getting to grips with our spending as a household.
That was long overdue and makes me feel one heck of a lot better about now having a plan. We’ve got a spending spreadsheet so we’re both updating to see the same picture together and will be targeting a $400 monthly food budget. [Yes, we eat too much. We’re cooking at home a lot more but we are piggies and one of us treats other people far too much. Ahem.]
One of my private loans came up this month, hence the leap from $12,630 to $15,900. I’m looking to reinvest again so that means I’ll keep the bit over $3000 and throw the $12,630 back into the investing pool. It takes nearly five years to come due so it’s what I’d consider a mid-term investment.
I also banked that surprise bonus and snowflaked all my bits of freelancey income towards the travel fund. It’s a little selfish since the other practical funds need attention but they will always be supplemented by the expense fund if necessary. The travel fund doesn’t get that luxury – it’s either funded or I don’t travel.
November’s rent is already covered because of a really stupid mistake. The October rent was already paid at the end of September but because it came out in the month of September, my brain didn’t click and I jumped mid-October to the conclusion that I hadn’t paid so I cut another check. Everyone roll your eyes with me. Who pays rent twice in a month?? Still, let’s take it as a good sign that it didn’t break the bank.
Speaking of banks, I moved a big chunk of money to Smarty Pig just in time for them to drop the interest rate to 1.75%, which is still higher than the 1.1% at ING. Excellent timing, self.
Overall, since I’m still occasionally sneezing about my parents’ financial situation via my financial situation, I’m still on the prowl for better places to store my money for higher interest rates (hah) and more income-producing opportunities.
October 30, 2010
Last Saturday, a strange young man knocked on my front door and earnestly asked if I’d take a free trial for a local newspaper for eight weeks to help him go to college. He was just trying to earn a scholarship for college, he said, and he just needed me to sign up, no money needed.
He said he couldn’t leave the sign up form with me overnight because his counselor collected them every day, but all he needed was for me to sign up. He’d take care of the fees himself, and that would earn him a $500 scholarship for college.
When asked which apartment he lived in, he gave an apartment number two floors up.
He did even try the “well, even the guy downstairs who doesn’t speak much English helped me out, he signed up,” waving a filled out form vaguely in my direction. [Translation: he was much easier to convince because he couldn’t understand the implications of what I might be trying to pull.]
Though he seemed nice enough, I was put off by a number of things. The fact I couldn’t place his face, the fact he gave no identification or the school he was with, he refused to leave the paperwork overnight, and the whole deal didn’t really make much sense. None of these were really conclusive signs of anything: I have a terrible memory for faces, don’t recognize half of PiC’s friends and coworkers with whom I’ve been out socially, and if he was an earnest teenager he wouldn’t necessarily know to win suspicious people over by presenting identification. Nevertheless, while I’m a bad people person, I’m also not the easiest person to scam specifically because I naturally don’t have a trusting nature. Even if I had allowed for all of the above and overlooked it (which I won’t), I didn’t like the idea of handing over my name and address to a complete stranger upon solicitation.
I won’t give it someone who seems official conducting a survey, why would I give that information to a kid literally come in off the street?
While there’s not a lot one could do with a simple name and address on the surface of it, that’s always a start if they wanted a name, address and a signature to start an identity theft ring.
The next day, a notice went out that the kid was part of a twosome who was confronted by a building manager and it was revealed that neither of them did in fact live in the building. Their business, then, was even if it wasn’t a scam, at the very least, not legitimate in the sense they were lying to the residents to gain their trust.
Do you think you would have been as bothered by all the little rather intangible things as I was? They were all gut instincts but even I thought they were a bit tenuous at the time.
October 27, 2010
You might have already heard about this from the granddaddy of all PF blogs, My Money Blog.
If not, those of you who invest with Vanguard index funds and hold more than $10,000 in those funds, you ay qualify to convert those funds to Admiral Shares.
A quick synopsis on Admiral Shares from their site:
Admiral Shares are a separate share class of more than 50 Vanguard funds that follow the same investment strategy as traditional shares, but with significantly lower expense ratios. They were created to recognize and encourage the cost savings that Vanguard derives from large accounts, and to pass those savings on to investors.
Thanks to their low costs, Admiral Shares can reduce your expenses 18%–50% below the already low expense ratios of our standard Investor Shares. (Find out why investment costs matter.)
For example, if you invest $50,000 in a fund’s Admiral Shares with a 0.07% expense ratio instead of its Investor Shares with a 0.18% expense ratio, you could keep approximately $1,200 more in net returns for your account over a 10-year period, assuming an average annual return of 8%. (This is a hypothetical illustration and does not represent any particular investment. Actual savings for your specific funds may be higher or lower.)
Only one of my funds qualified for conversion so I swapped that right over. I’m no longer actively contributing to my Vanguard funds at the moment but the Roth IRA could use a fresh infusion of funds when I’m ready to let go of some cash. My current accounts stand at $42,768.87 and I’d like to break $50,000 by this time next year [for the record: October 26th, 2011] so I need all the help I can get.
Be sure to take advantage of the lower expense ratios in the Admiral Shares if you can!
October 26, 2010
Winter is fast approaching, and while PiC regularly twits me about what I think is cold, we both know my winter wardrobe is woefully lacking. I have one really good knee-length BCBG coat, lined with a gorgeous silk, bought years ago, one hip length pea coat, a lightweight knee-length trench coat, and four sweaters of varying weight. In combination with a couple of basic scarves from H&M, I always figured that was good enough but that won’t do here.
Even if it doesn’t get much colder, SF will get much wetter! The rain has already begun so actual raingear is in order. For my upcoming travel to colder climes, a raincoat, a set of hat, scarves, gloves and boots are an absolute necessity. Time’s running out so I cracked my online shopping knuckles and got to work.
I’ve picked up three more long sleeved shirts from Ann Taylor marked down to the standard $20/shirt that I have had to pay for that kind of layer because I wear the heck out of the three long sleeved shirts that I currently own already. They’re already starting to show a bit of wear because they’re so frequently used. If I find a better bargain for equal quality, though, I’m happy to go with that! It’s a shame I don’t have time to trek out to the outlets.
One major coup was scored last week: I have acquired my very first pair of rainboots!
Thanks to the lovely PetiteAsianGirl‘s recommendation, I tried the dav City Rain Boots. I wanted them in classic black, but they were full price ($49.99) in black and on sale for $35.66 at Amazon where I could get free 2-day shipping in a different color.
Houndstooth is just as classic and a wee bit more interesting so I’m now the proud owner of these darlings:
I still don’t actually know what you DO with them, precisely … I wear slacks and trousers and hate carrying anything more than is absolutely necessary but would I have to wear socks with these and pack flats to change into? I only wear trouser jeans when I wear jeans to work – must I switch to skinnies so they can be tucked in? And then tromp around all day in them?
They don’t half baffle me when it’s for casual wear but take it to a professional level and I’m at a loss.
Anyway, I’m hoping the rest of the shopping will be as fruitful, bargainalicious and right-sized! Your recommendations for professional shopping destinations carrying petite sizes would be greatly appreciated.
Left on the list
Warm, lined gloves for small hands – preferably something waterproof as I hate having soaked, cold fingers
A nice hat, also preferably waterproof, good for 20-40 degree (F) weather
Thick, warm scarf that doesn’t shed.
1 more turtleneck
Down, quilted vest, I think these almost always run more sporty than professional but I’m going to need it.
October 25, 2010
After a wonderful meal at a Korean tofu house with a friend we hadn’t seen for a few months, she wanted to make plans to meet for dinner again during the week before she left town.
That same day, I received a message from another friend who recently relocated to this coast. She planned to be in town to see family, could we have brunch when she landed Saturday? When I wasn’t available, she asked if we could come out to see her across the way Sunday. Though she didn’t specify it was a full day thing, history shows that’s going to be expected. All previous “come hang out with me” invitations have always turned into a day-long finagle-fest because she always wants to do just one more thing.
Don’t get me wrong, I enjoy her company but it’s really hard to commit full days to hanging out at the last minute like that because I’m usually running like a madwoman during the week to survive and use the weekends to become human again. Which, as you might imagine, is a little complicated after September’s hosting visitors every weekend (and seeral weekdays) but one.
That’s the crux of it, isn’t it? I quite enjoy seeing friends, of course, but the last minute requests and those that sometimes grow well beyond moderation are rather difficult to accommodate. Or even to want to accommodate; it requires a sanity check to make sure we’re not just constantly running to everyone’s beck and call because they’ve dropped in and didn’t we want to see them?
Sure, but I think it becomes taken for granted that we’ll always be available on their schedule and doesn’t call for much advance notice. That drives me, an inveterate planner, at least a little up the wall. I understand that not all trips are planned as far ahead as I would like but these texts and emails are increasingly and frequently coming with very little notice.
Aside from the limited time factor, I worry about the money we’re spending hand over fist with this stream of visitors. When we host, I can cook and feed them relatively (not very) frugal basis. But many times, we end up eating out because they’re in the city, we’re not, and it’s inconvenient for them to come to us and then trek back to the city.
While PiC and I have agreed on a rule of thumb on eating out, my personal budgeting rules have always stated that “entertaining” comes out of the same eating out allowance lest we end up using the personal 2x/week allowance, and entertain two or three times on top of that. Before you know it, we’ve spent most of the week eating out. My personal budgeting rules have been repeatedly smashed under the weight of the last minute traveler.
We can’t control the travel habits of our friends, and we certainly never want them to feel unwelcome or unloved, but it’s time to gently nudge them toward better notification habits. And we need to learn to set boundaries we’re comfortable with rather than self-guilting ourselves into doing far more for them than is necessary.
Do you have any trouble managing drop-ins or do you have a good standing policy that works well for you and yours?
October 23, 2010
My letter of doom arrived on October 15th. It was a Friday. It was a payday. It was, in all other ways, good. Then the letter arrived.
A thin envelope from Chase which had no business being here, no rewards check having been ordered recently, no changes to terms or conditions anticipated. No reason at all for this surprise delivery from the postperson.
That envelope contained a missive from my former favorite bank/credit card stating that my go-to credit card, my Chase Cash Plus, 5% cash back on all gas, groceries and drugstores card was being converted into a Chase Freedom card.
FREEDOM. Freedom they call it. Freedom to go …. never mind. Freedom it is, then.
Freedom to earn a paltry 1% cashback on all purchases and a bonus 5% for three short months on their select categories of the season. This winter (Oct 1-Dec 31st) will be groceries, department stores and movie theatres. Never ye mind I don’t shop at department stores or go to movies more than few times a year, forget during these three months of the year. The pink French washed sea salt in an already searing wound? A customer is now required to sign up every three months for the categories for which they desire the bonus % cash back.
O bitterness! There was much rending of garments and remonstration.
**For the record, PiC was puzzled and unmoved. He clearly has some conversion to the world of personal finance left to do. Now I have to find a better go-to card. Bischla.