About sixteen years ago, I met him for the first time. My trainwreck sibling brought home this adorable puppy he had no business adopting because he had not one thing in his life that wasn’t a mess. I was furious at my sibling – he didn’t even take care of himself, how could he drag
Read More
September 11, 2008
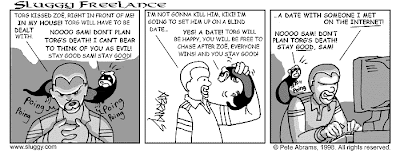
Every time I think of WAMU potential failing, I think of my checking account, my three year supply of animal checks, and inevitably, Kiki. She’s a Sluggy Freelance character, a ferret who’s terribly attached to her friend Sam, a vampire. She’s always exhorting, in any given situation, for him to “Stay Good, Sam!” It’s a completely unrelated webcomic, having only the slightest of relevance to anything, but it still amuses me.
For a much more mature analysis of the state of affairs, Flexo’s really the man.
On a personal note, I’ve had a checking account with WAMU since I turned 18, and have been using this batch of checks since 2001. That’s really the main reason I’ve kept this account: I don’t want to pay for any more checks while I still have at least a good 300 checks left. They do have decent customer service for my free accounts, so I usually keep a minimal amount of money in there and transfer money from the Citi account as necessary to round out the checks I write.
It’s not comforting that my two primary B&M banks aren’t exactly stable, but I do have an ING account from which I could open an Electric Orange checking account in a pinch. That shouldn’t take too long. There’s probably about $500 in the WAMU account right now, and I’ve considered transferring it all to my Citi account to avoid the inconvenience of dealing with FDIC insurance if it comes to that. Taking out my $500 wouldn’t make a difference in the whole scheme of things, I’m just small fry, but if everyone took out their money, creating a run on the bank, that’d be a shame. Hm…
A friend posed this hypothetical question to me recently, and the ensuing bickering reminded me that I don’t play hypothetical money games well:
If your car was completely totaled and someone gave you a lump sum, say, $30,000, to buy a car, what car would you buy? (And you have to spend ALL of it on the car.)
*grimace* Eh. That’s too much to spend on a car, for me. Even given the hypothetical donor, even given the no-strings-attached, even given that the money’s not coming out of my pocket, I couldn’t really get all that enthused about the idea.
Honestly? I like my car. I like the mileage, I like the size, I’m comfortable in it, I like that it’s not brand new anymore (except for those little “personality quirks” she’s developing). If she was *sob* destroyed, I would … want the same car. Boring? *shrug* Yeah. But they don’t make her anymore, so I’d have to get a used version, which is fine, I’m D-O-N-E with new cars, new car insurance, new car registration and all that being oh so careful where I park because I’m driving a new car.
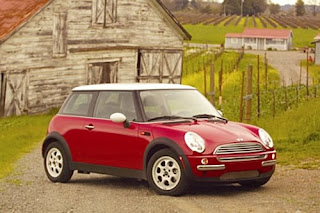
Admittedly, there’s a bit of me that still likes the MiniCooper, the Mazda 3, and remembers that I did say I wouldn’t be buying any more two door cars so getting the same car wouldn’t make sense but …. uh, let’s just say that all the fun of asking me a hypothetical question like that was long gone.
So how about it, folks? What would you get with a $30,000 (to replace your destroyed vehicle) budget? And yes, same parameters: If I had to spend it all, so do you! 🙂
I’ve used my impulse buy twice now, and I love it. I might like it more than my dog does! She loves the attention and fuss, but remains wholly unimpressed by the bags of fur collected during the grooming session.
She’s giving me the side-eye here because I can’t hold her paw AND keep brushing. Oh, and taking a picture instead of brushing? UNacceptable.
September 10, 2008
Just as I was thinking that the iPhone was slowly redeeming itself …. ok, I can’t blame this on the phone, it’s totally my fault.
I had my bag in my lap, and was reading Astonishing X-Men #4 this morning when, one station from my final destination, I heard *slither — thunk!* Immediate reaction: oh no! Sure enough, the phone had slipped out of my bag and fallen between my seat and the wall of the train. Um. Since my hands are pretty small, and I always have to fish papers and such from between my desk and the wall at work, I thought I could use a pen to lever the phone high enough so that I could pull it out.
No dice. Not only did the pen not reach, I hit the phone at just the right angle to push it down further on its side. The next tool I tried, the comic book (I was getting desperate), knocked it flat on its face. Crap!
I tried coming at it from the other side of the seat bank, no luck. I tried going under the seat, but there was only two cms of space between the ledge the phone was on, and the stupid face extending from the bottom of the seat. My hand totally didn’t fit. Eventually, I went to get the conductor, and he only succeeding in pushing the phone completely under the seat so we couldn’t even see it any longer. Rats rats and rats.
At this point, we’d missed our shuttle to work, and I was red with frustration and embarrassment. Stretched out underneath the seat, trying to see harder (no, that didn’t work), and make my hands smaller, I thought, “This is completely ridiculous!!” And friend chimes in, “Yeah! But it’s better than being at work!!” *sigh* I guess it is … which speaks volumes. The conductor gave us five minutes to work on it before he had to take the train to the Yard, at which point they’d have to remove the seats to reach the phone. We thought we were *really* going for a grand adventure at that point, but he kicked us off the train and told us he’d call when they retrieved the phone. We ended up running alongside the train yelling names and phone numbers for him to reach us, as the trains pulled away from the station.
That’ll teach me to complain about my phone. I feel like I just got taught a lesson about being grateful for what you have. 🙁
September 9, 2008
I’m mustering some optimism about the next couple of months. It’s not just because my August net worth managed to hold steady with a miniscule increase despite the market and my doing very little to save.
That most definitely helped, but last night I charted my expected income/expenses for September and found that if I stick with the plan through the month of October, I should be able to finally build that paycheck cushion I’ve been wanting. There are only a thousand articles about not living paycheck to paycheck, and while I’d made progress over the past two years, a few setbacks had punted me back into a check-to-check reality.
I can’t for the life of me find the blog article that I had printed out and still keep in my folder, so I can’t give credit where it’s due but there was a great post simplifying the transition from using this month’s money for this month’s bills to using last month’s money to pay this month’s bills. If anyone knows the blog post I’m talking about, I’d love to credit and link them!
That was what I originally had in mind when I instituted my current billpay system: I give myself a biweekly allowance for expenses, and that money sits in an interest bearing account while I pay bills from it. In fact, I wanted to do one better and have a two-month cushion so that I could concentrate on other savings goals, both long and short term, and be ready in case I ever needed to say “I’m outta here!” My emergency fund is more of a disaster and medical emergency fund. (With my family? Can’t be too safe.)
Back to the point.
At the end of September, assuming there aren’t any more surprise bills, and my supplemental income is paid on time, I should have approximately $900 left for expenses. Thanks to getting my insurance money back, the expense account is finally out of the red.
Second, I expect to log at least 40 hours of overtime this month, and I’m splitting all overtime income between expenses and savings, 50/50. I don’t have a dollar amount for that income, but I’ve set the total cushion goal at $3300. I won’t depend on “windfall” money to pay the actual bills in the future, it was just the weird way I get paid and the other expenses depleted the original cushion. [The flip side of that negatroid coin is that I had the funds there to use in the first place. No debt, whoo!]
Third, October is my three-paycheck month. By September’s end, I should have enough in the cushion to cover half a month’s expenses. I’ll take that entire third paycheck and split it between expenses and savings as well. But, if I hit my $20,000 emergency savings goal before October’s third check, then the entire third check can go towards the expenses fund!
If all of the above happens on schedule, without any hiccups, I can get off this paycheck to paycheck cycle by the end of October. How cool is that?
September 7, 2008
I’ve sent emails galore, one for every category:
* Queried friend of a friend about her work environment
* Finally found a lost email, sent to deprived friend
* Sent two networking base-touching emails from the networking event I attended last week. (Two weeks ago? Aren’t you supposed to send those out a day or two after meeting people? I know, I’m a slacker.)
* Sent love to sick friend
Still to go:
* Find a scanner. Perhaps I shouldn’t be trying to buy one, though I’m enamored of those multipage scanners for about $200 on newegg.com. Will check if my friend has one that I can use.
* Use aforementioned scanner to clear out tons of paperwork.
* Online research. Of the life changing kind.
* Applying results of online research.
* Engage Dad in conversation about Mom’s health care, health care providers, health care visit, dietary needs, budgeting, saving, and future plans. Make that conversations. We’ve lightly touched on the subjects, but desperately need to sit down and make actual, concrete plans.
* Get some sleep between now and next week — I need to rest up before this lack of sleep makes me look like a 13-year-old. Between hormones and tiredness, I’m starting to break out. Yikes!
September 5, 2008
Oy. No, no I don’t. But because I clicked on the link … I found that I do, perhaps, need ….
Women’s Xhilaration® Susan Plaid Mary Jane Pumps – Black: $22.99
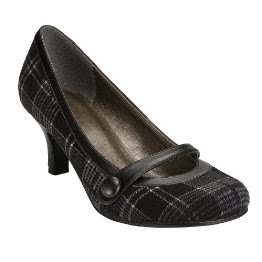
Women’s Mossimo® Viviana Pumps – Black: $24.99

Ok. So here’s how I’m going to talk myself OUT of them:
1. I have too many shoes. I don’t like having too many shoes, and have actually gone through and donated three or four pairs recently to start paring down.
[Except, I only have one pair of black pumps and they’re so scuffed now. All my other shoes are open toed, or a leetle too shiny for business purposes. My mind is still on interview styles.]
2. And I’m not supposed to be buying cute things just because the price is low and they’re cute. They have to be good quality as well.
[Objecting voice has no objection to this.]
3. I’m not allowed to spend money right now. I have this whole PLAN set up. A plan that I’ll share once I confirm more of the details.
[Oh. Yeah.]
Dangit, Target!!


